What Is X Money?
What Is X Money?
Why did Elon Musk add financial services to a social app?
X is the social platform formerly known as Twitter. People post writing and videos there and follow what others share. Elon Musk has added a financial service called X Money. Three questions make it easier to understand: what can it do today, how does it differ from a bank or payment app, and why put money inside a social platform?
What can X Money do?
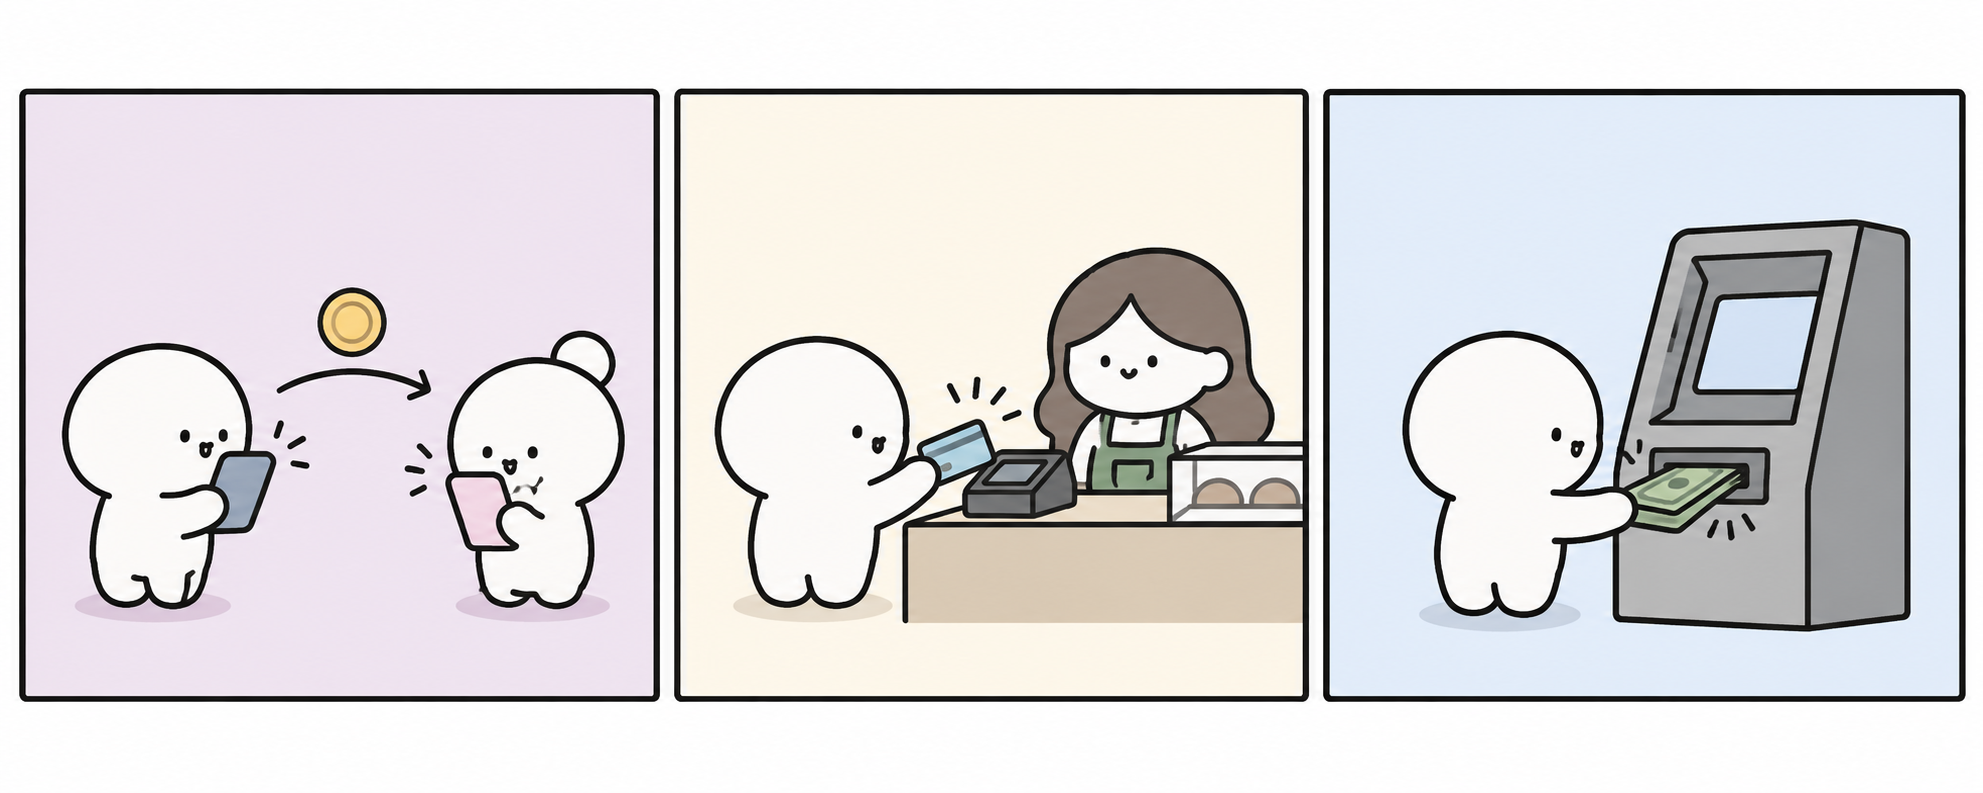
Start with familiar tasks. You can put money in an X Money account, send it to another X Money user, or request a payment. You can spend the balance with an X debit card, withdraw cash at an ATM, or move it to another bank account. Direct deposit and interest are also offered. These features live in the Money tab of X.
You can add physical cash, too. In the Money tab, choose Add Money → Cash and find a participating retailer on the map. Hand the cash to the cashier at the register; X says it is usually added within minutes and the cash load at a participating store is free.
An ATM deposit is outside that free network and its operator may charge a fee.
Suppose you owe a friend $30 for lunch. If both of you have X Money, you find the friend in Money, enter the amount, and send it. X says person-to-person payments are free. Check the recipient and amount carefully: a completed payment generally cannot be reversed.
The X Card works like a bank debit card. When you pay in a shop or online, or take cash from an ATM, the money comes from your X Money balance. It is not credit that you pay back later. Virtual and physical cards are available, and card purchases and ATM withdrawals have limits.
Access is still rolling out to selected U.S. users as of September 2026. You must be at least 18, live in the U.S., have a verified U.S. phone number, and have an X account in good standing. A paid Premium subscription is not required to open an account.
How is this different from a bank or payment app?
Paychecks, cards, and transfers already exist. X did not invent sending money. Its move is to let people exchange money inside the same X app where they read posts and talk to others.
Zelle is a useful comparison for sending a friend money. X Money extends beyond that single task: you can hold an account balance, earn interest, receive a paycheck, and pay with a debit card.
The ease of sending money from a social app also makes it important to verify the person and the transaction. A familiar profile alone is no guarantee of safety.
Did X become a bank?
No. X Payments LLC is not a bank. Deposit accounts are held at Cross River Bank. X provides the app experience, and the card uses the Visa network. The X logo on the screen does not mean X itself holds the deposits.
Eligible deposits have standard FDIC coverage of $250,000 per depositor, per insured bank, per ownership category. X says its cash sweep program can spread deposits among participating banks for up to $10 million in aggregate pass-through coverage, subject to conditions.
FDIC coverage addresses an insured bank’s failure. It does not insure a mistaken payment or an investment loss.
Does everyone earn 6%?
No. Under X’s published variable rates effective July 27, 2026, the standard APY is 4% for users with no subscription, Basic, or Premium, and 6% for Premium+. Other users may qualify for a 6% boost when qualifying direct deposits processed as ACH PPD, or specified X creator payouts, total at least $1,000 within the preceding 34 days. This does not mean making a deposit every day.
One $1,000 paycheck can meet the threshold; when it falls outside the rolling 34-day window, the boosted-rate condition is no longer met unless new qualifying deposits have arrived. Continuing to qualify therefore takes qualifying deposits over time.
A cash load at a store or an ordinary transfer from another bank does not by itself meet that boosted-rate condition. Interest is currently unavailable to New York residents.
For perspective, $10,000 at 4% would earn roughly $400 over a year; at 6%, roughly $600. That is a simplified pretax illustration assuming an unchanged balance and rate.
Actual rates and returns can change. The subscription price changes the calculation. X lists Premium+ on the web from $40 a month or $395 a year, with location, taxes, and payment method potentially changing the total. On a constant $10,000 balance, the extra two percentage points over the standard 4% would produce about $200 in additional pretax interest over a year—less than a $395 annual subscription.
Buying Premium+ for that interest alone would not pay for itself at a $10,000 balance. In this simplified comparison, $395 divided by a two-percentage-point difference implies a break-even average balance of about $19,750. Variable rates, taxes, and the value of other subscription features are separate considerations.
What if I put in $10,000 in cash?
First, check whether X Money has reached your account. If it has, use Money → Add Money → Cash to find a participating store and check your deposit limit. Do not assume you can load $10,000 in one visit: limits vary by account and activity and appear under Settings → Limits. You could also transfer funds from another bank by ACH.
The interest rate depends on your eligibility, not the way you added the money. A user who only loads cash and has no Premium+ subscription would receive the published standard 4% APY.
Premium+ users are eligible for 6%. Other users need a separate $1,000 total from ACH PPD direct deposits or specified creator payouts in a trailing 34-day period to earn the boosted 6%.
Interest uses the daily balance and is paid monthly. Roughly $600 on $10,000 at 6% is only a pretax illustration if the balance and variable rate remain unchanged for a year.
To move the money back to another bank, a standard ACH withdrawal is free and usually takes one to three business days. An instant withdrawal costs 1.75%, with a $0.25 minimum.
ATM cash withdrawals are also available, but reimbursement of an ATM operator’s fee depends on subscription tier. Loading cash at a retailer and withdrawing it at an ATM are different processes.
Why does Musk want money in X?
Musk founded the online finance company X.com in 1999. It merged with Confinity in 2000 and later became known as PayPal. Today’s X Money is not a continuation of those old accounts, but the interest in moving money online has a long history.
In 2022, Musk said buying Twitter would accelerate his idea for an “everything app.” X Money turns part of that ambition into actual features. Transfers, accounts, and cards are available now to eligible users. Closer ties between payments, commerce, and creator activity are a possible direction, not a promise that every imagined feature already exists.
X Money lets eligible users send money and use an account balance for debit card purchases and ATM cash. X itself is not the bank. Whether the broader vision succeeds will depend on how clearly the service works and whether people trust it with everyday money.
Sources and terms: X Money FAQ · account rates · Cross River Bank announcement. Checked September 28, 2026. Availability, rates, and fees may change.